The 70% rule is a fast screening formula for a fix-and-flip. It estimates the highest purchase price that might leave room for the rehab, the costs of owning and financing the property, the cost of selling it, and a profit.
It is useful because it is fast. It is dangerous when it is treated as a valuation, a loan approval, or proof that a deal works. Use it as the first filter — not the final answer.
On this page
The 70% rule formula
ARV means after-repair value: the expected resale price after the planned work is complete.
The missing 30% is not a magical safety margin. It is a rough allowance for everything the simple formula does not list separately: purchase closing costs, holding costs, financing, selling costs, mistakes, and profit. If those real costs are higher than the rule assumes, the rule gives you too high a ceiling. If they are lower, it may be unnecessarily strict.
Worked example
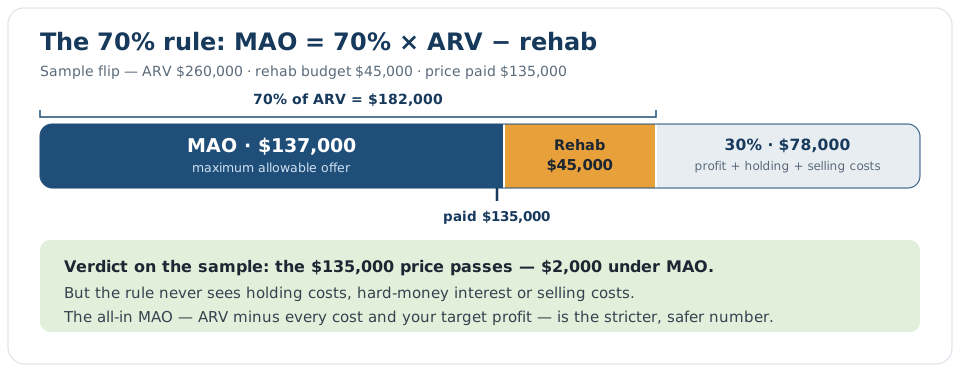
Use this sample deal: purchase price $135,000 · rehab budget $45,000 · ARV $260,000 · hold 6 months · hard-money loan 85% of purchase price plus rehab at 12% interest-only, 2 points · selling costs 7.5% of ARV.
| 70% rule — the sample deal | Amount |
|---|---|
| ARV (after-repair value) | $260,000 |
| Estimated rehab cost | $45,000 |
| 70% × ARV | $182,000 |
| Maximum allowable offer (MAO) | $137,000 |
| Purchase price | $135,000 |
| Cushion under MAO | $2,000 |
Legend:Yellow = inputsGreen = calculated
The $135,000 purchase price is $2,000 below the $137,000 ceiling, so the sample passes the 70% rule. That $2,000 cushion is thin. It does not mean the deal has only $2,000 of risk, and it does not guarantee the projected profit. It means only that the price passes this one shortcut.
What the full calculation shows
A complete model separates the costs the rule compresses into its 30% allowance:
| Item | Amount |
|---|---|
| Purchase price | $135,000 |
| Purchase closing costs, 2% | $2,700 |
| Rehab | $45,000 |
| Holding costs, $650 × 6 months | $3,900 |
| Hard-money points, 2% of $153,000 | $3,060 |
| Interest, $1,530 × 6 months | $9,180 |
| Total project cost | $198,840 |
| ARV | $260,000 |
| Selling costs, 7.5% of ARV | −$19,500 |
| Net sale proceeds | $240,500 |
| Net profit | $41,660 |
The loan is $153,000: 85% of the $180,000 combined purchase price and rehab budget. Cash invested is therefore:
And the return on that cash is:
The break-even sale price is $214,962. Below that sale price, after the 7.5% selling costs, the sample deal loses money. Those extra numbers are the reason the 70% rule should start the analysis rather than end it.
ARV must come from sold properties
The formula is only as honest as the ARV inside it. An asking price is not an ARV. Neither is the highest sale in the neighborhood, a seller's estimate, or a renovated property that is materially larger, newer, or in a better location.
Build ARV from closed sales of comparable properties, then adjust for differences that matter:
- Living area, lot, beds, baths, garage, and layout
- Condition and quality of renovation
- Location within the neighborhood
- Sale date and changing market conditions
- Features that buyers in that specific market actually pay for
Use the planned finished property as the comparison point. A house that will have a basic rental-grade finish should not be valued from a designer renovation. A property with an awkward layout does not become comparable to a clean, functional plan just because the square footage is similar.
Then be conservative about the adjustments. If the ARV requires every uncertain judgment to break in your favor, it is not an underwriting number — it is a hope.
What the 70% rule ignores
The rule does not know your actual deal. In particular, it does not separately calculate:
Holding time and holding costs
Taxes, insurance, utilities, HOA dues, lawn care, security, and other monthly costs continue whether the project is moving or stalled. In the sample, holding costs are $650 per month, or $3,900 over six months. A delayed permit, a contractor problem, or a slow sale can extend that period. The 70% rule does not adjust when the hold changes from six months to nine.
Financing structure
Two loans with the same interest rate can produce different costs. Points, lender fees, draw procedures, extension fees, interest reserves, and whether interest is charged on the full loan or only on drawn funds all change the result. In the sample, financing costs are $12,240: $3,060 in points plus $9,180 of interest. Another lender or a longer hold would produce a different number.
Purchase and selling costs
Closing costs apply when you buy. Commissions and seller closing costs apply when you sell. In the sample, those are $2,700 at purchase and $19,500 at sale. The rule leaves them inside its rough 30% allowance. Your settlement statements will not.
Rehab accuracy
Subtracting a guessed rehab number is the easiest way to make a bad deal pass. A $45,000 rehab entered into the formula should be a category-by-category budget, not a round number chosen because it makes the offer work. If the rehab is really $60,000, the same ARV produces a very different ceiling:
The rule did not fail there. The input did.
Your required profit
The formula does not ask what profit compensates you for the capital, time, execution risk, and possibility of a market change. One investor may require a fixed dollar amount. Another may underwrite to a margin or return target. The 70% rule substitutes a generic allowance for that decision.
When the rule is too strict — and when it is too loose
The rule can be too strict when the rehab is light, the hold is short, financing is inexpensive, selling costs are low, and the ARV is strongly supported. A deal can fail the shortcut and still meet a carefully documented target.
It can be too loose when the rehab is uncertain, the property will sit through a long renovation or listing period, insurance and taxes are high, the loan carries heavy points and fees, or the ARV depends on the best possible comparable sale.
That is why a failed 70% test is not an automatic rejection and a passed test is not an automatic purchase. It is a prompt to run the full numbers.
Stress-test the shortcut
The sample's projected profit is $41,660. Small changes to the two biggest assumptions change the story:
| Scenario | Net profit |
|---|---|
| Base case | $41,660 |
| ARV falls 20%, rehab stays on budget | −$6,440 |
| ARV holds, rehab rises 50% | $17,630 |
| ARV falls 20% and rehab rises 50% | −$30,470 |
The deal is especially sensitive to ARV. That does not make it a bad deal, but it tells you where to spend verification time: on the sold comps and the realism of the finished value.
Common mistakes
- Using list prices as ARV. Closed sales are evidence; asking prices are marketing.
- Entering a rehab guess. Build the rehab from categories and quotes before trusting the MAO.
- Treating the cushion as profit. A price below MAO is not the same thing as money earned.
- Ignoring the calendar. Every extra month adds holding and possibly financing costs.
- Raising ARV to rescue the deal. If the offer only works after optimistic adjustments, the problem is the price or the project — not the formula.
- Stopping at PASS. Check profit, cash invested, break-even price, and downside cases before making an offer.
Bottom line
The 70% rule is a useful first screen: MAO = 70% × ARV − rehab. For the sample property, it produces a $137,000 ceiling, and the $135,000 price passes by $2,000. The full model projects $41,660 in profit on $45,840 of cash, but a 20% ARV miss turns the same deal negative.
Use the rule to decide which properties deserve a complete underwrite. Do not use it as the underwrite.
Try the free House Flip Analyzer Lite first to run the core flip calculation and 70% rule check on one sheet. The Full version adds sensitivity analysis, financing detail, break-even analysis, and the project tools — rehab budget, expense log, contractor quotes, change orders, payments, timeline, and dashboard — when you are ready to underwrite and manage the whole deal.
Get the free Lite
Already sure? Get the Full version:
Buy — PayPal / card ($24) Buy — crypto ($24)Two checkouts, same file: PayPal (card or balance) or crypto (USDT/USDC).